ECONOMIC OPINION & ANALYSIS | OCTOBER 2026
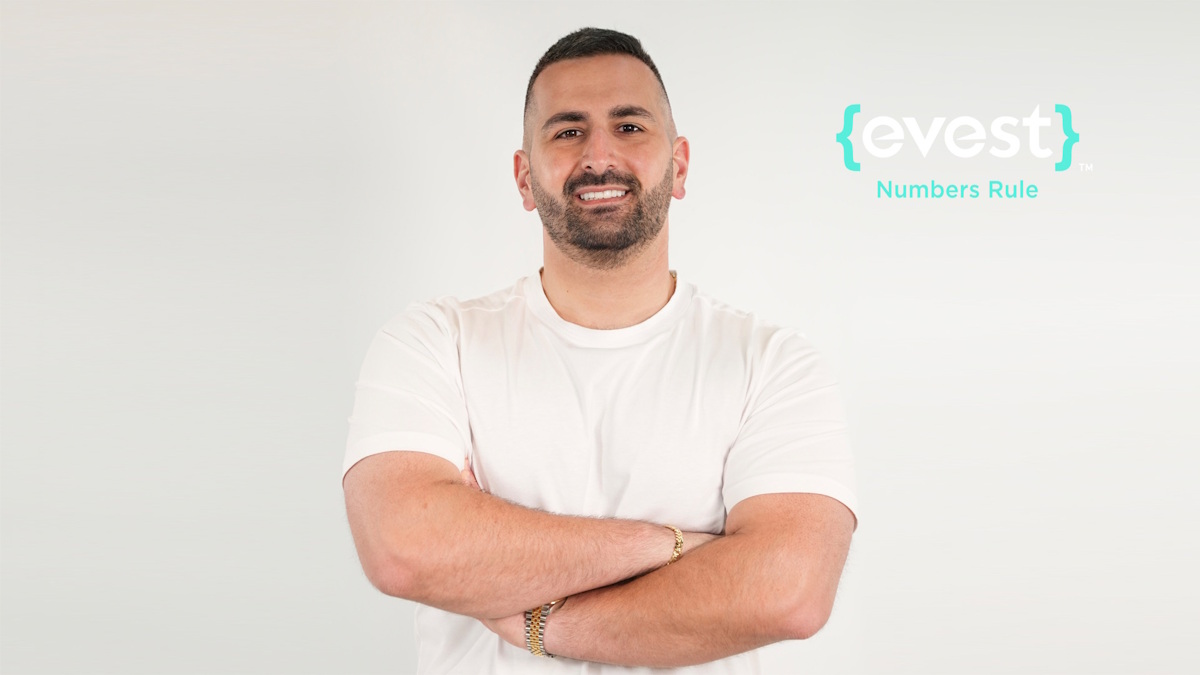
By Wael Rashed | Director of Business Development & Corporate Spokesperson, Evest
In a world where economic power dynamics are shifting and geopolitical developments are accelerating, the most pressing question is no longer whether the global economy can overcome crises. Rather, it is whether the stability we are witnessing reflects genuine economic strength or merely a temporary equilibrium concealing widening structural imbalances.
In recent years, the global economy has demonstrated a remarkable ability to absorb shocks, from supply-chain disruptions to inflationary surges and tighter monetary policy. Yet, as Wael Rashed observes, this resilience raises a paradox worth examining: Has the speed of market recoveries led us to underestimate the risks accumulating within the financial system?
Economic Growth Does Not Necessarily Mean Stability
According to World Bank estimates published in June 2026, global growth is expected to slow to 2.5% this year, down from 2.9% in 2025, amid mounting pressures from higher energy and financing costs and geopolitical tensions.
For Wael Rashed, the deeper issue is not simply slower growth but the nature of the forces sustaining it. An economy increasingly reliant on credit expansion, government spending, and rising financial-asset valuations may remain active for an extended period without necessarily developing a more sustainable productive base.
This highlights the divergence between financial-market performance and economic reality: markets may post substantial gains even as businesses and households face higher borrowing costs and pressure on purchasing power.
Global Debt and the Limits of Resilience
High debt levels represent one of the most significant tests facing the global economy. According to the Bank for International Settlements’ 2026 Annual Economic Report, elevated public debt, alongside the growing role of non-bank financial institutions, has become an increasing source of financial risk.
As Wael Rashed emphasizes, the danger lies not only in the size of the debt burden but also in governments’ ability to service it without cutting productive spending or adopting fiscal measures that weigh on economic activity.
As bond yields rise, borrowing costs place greater strain on public budgets, limiting governments’ capacity to intervene when new crises emerge. Consequently, debt once used to shield economies from contraction could become a factor that weakens their ability to withstand future shocks.
Financial Markets: Between Confidence and Overvaluation
Financial markets depend on expectations as much as on economic fundamentals. Rising stock prices or an improvement in risk appetite, therefore, do not always provide sufficient evidence that the underlying economy is sound.
In its April 2026 Global Financial Stability Report, the International Monetary Fund warned of risks associated with high indebtedness and leverage among non-bank financial institutions, as well as concentrated valuations in certain sectors, particularly companies linked to artificial intelligence.
Wael Rashed notes that this does not necessarily mean markets are in a bubble. It does, however, point to a potential gap between investment expectations and the economy’s actual capacity to translate those expectations into lasting productivity and profits.
When confidence becomes overly dependent on continued liquidity and rising asset prices, markets grow more sensitive to sudden shifts in expectations.
From Crisis Management to Building Economic Resilience
Genuine economic stability cannot be measured solely by the absence of crises or the speed at which financial indicators recover. It must also be assessed by the economic system’s ability to withstand shocks without repeatedly requiring extraordinary intervention.
In Wael Rashed’s assessment, this calls for a reassessment of economic policy priorities: moving beyond support for short-term growth toward higher productivity, sustainable public finances, and stronger oversight of risks outside the traditional banking sector.
Greater market transparency, more diversified sources of growth, and the rebuilding of governments’ fiscal buffers are no longer reforms that can be postponed; they are essential conditions for more durable stability.
Real Stability—or the Calm Before the Test?
It would be inaccurate to claim that the global economy is inevitably on the verge of another crisis. Equally, it would be unwise to treat its past resilience as a guarantee of future stability.
Economic history teaches us that major imbalances do not always emerge during downturns; they can also accumulate during periods of optimism and relative calm.
For Wael Rashed, the real challenge facing the global economy is no longer merely to avoid the next crisis, but to ensure that the cost of overcoming it does not exceed what the economy can bear.
Stability grounded in strong productive and financial foundations is fundamentally different from stability that depends on favorable conditions continuing indefinitely.
Perhaps the question policymakers and investors should be asking today is not “How long will this stability last?” but “What will remain of it when the conditions that created it change?”
Sources and References
World Bank — Global Economic Prospects (2026): https://www.worldbank.org/en/publication/global-economic-prospects
Bank for International Settlements — Annual Economic Report (2026): https://www.bis.org/annualeconomicreports/index.htm
International Monetary Fund — Global Financial Stability Report (2026): https://www.imf.org/en/Publications/GFSR
This economic opinion article reflects the author’s views and does not constitute investment advice.